
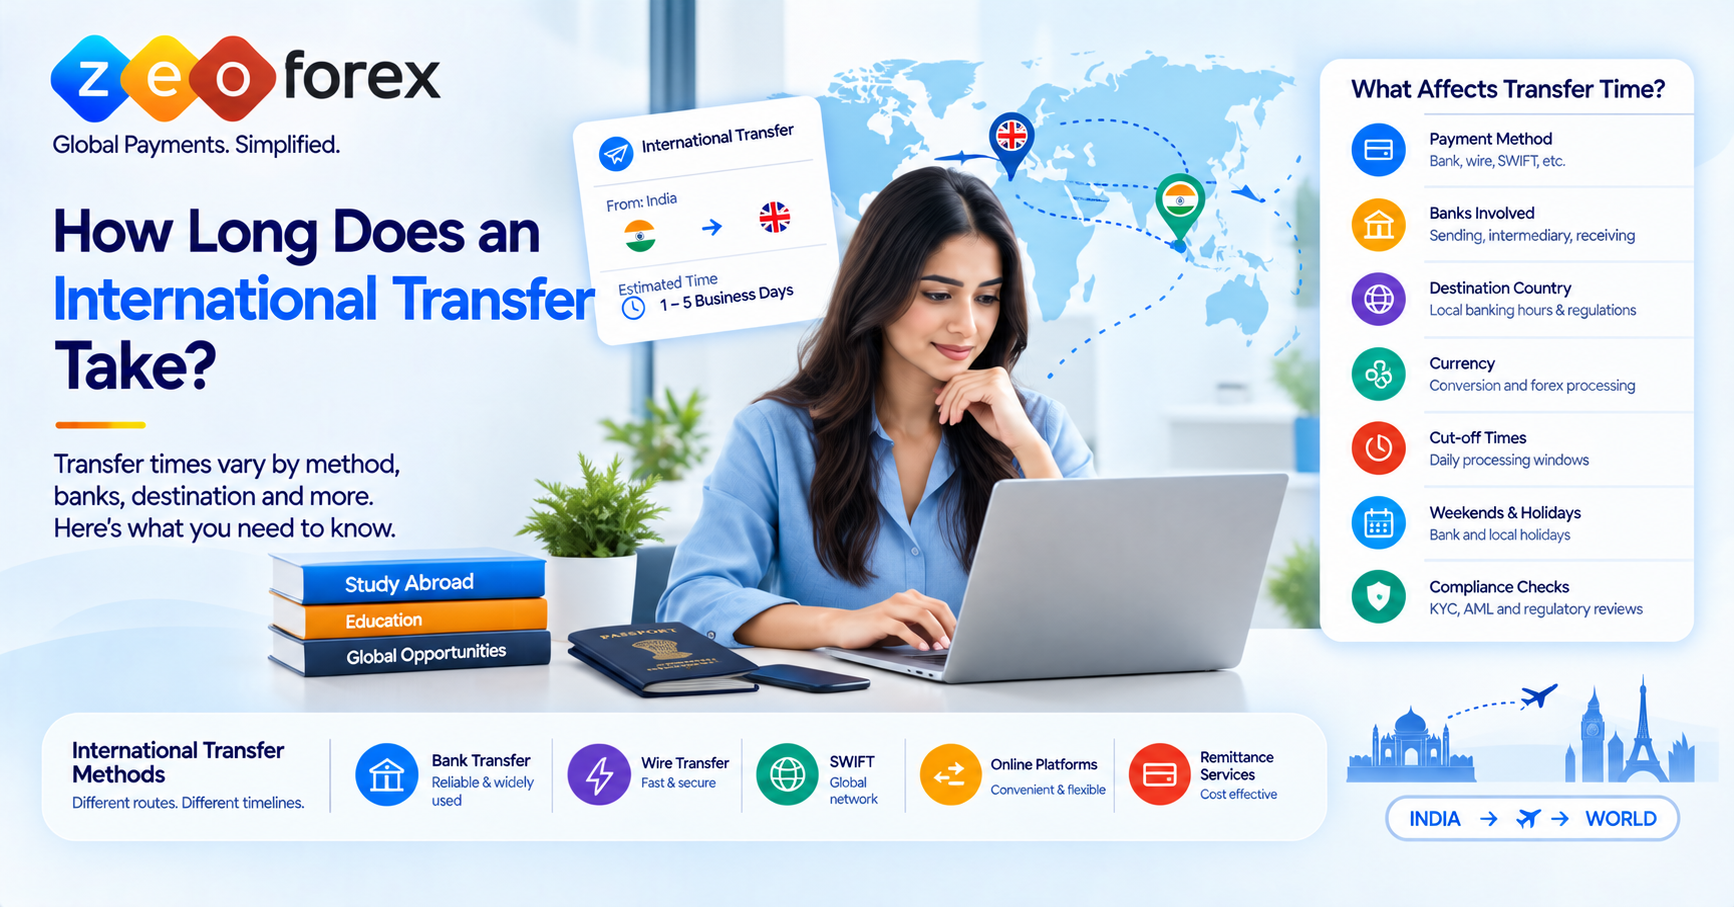
An international transfer usually moves through several stages rather than one single step, and the total time depends on the payment method, the banks involved, the destination country, the currency, cut-off times, weekends, holidays and any compliance checks along the way. There is no single number that applies to every transaction, since a payment can move quickly between institutions but still take longer to actually land in the recipient’s account.
Quick Answer
International transfer times vary by payment method, the banks involved, destination country, currency, processing windows, cut-off times, weekends and holidays, intermediary institutions and compliance checks. A transfer can move quickly between financial institutions but still take longer to reach the recipient’s account because of receiving-bank processing and local requirements.
How Long Does an International Money Transfer Take?
An international transfer generally follows this journey:
Transfer initiated → sending institution processes the payment → payment travels through the relevant banking or payment infrastructure → receiving institution receives the payment → local processing and checks → funds credited to the recipient
The phrase “transfer time” can actually mean a few different things, and mixing them up is where most confusion comes from.
| Term | Meaning |
|---|---|
| Processing time | Time taken by the sending provider or bank to process the instruction |
| In-flight time | Time while the payment moves through the cross-border payment chain |
| Settlement | Completion of the relevant payment or settlement process |
| Delivery or credit time | Time until funds are actually available in the beneficiary’s account |
This distinction matters more than it might seem. SWIFT’s own data shows why: a payment can reach a beneficiary bank very quickly, but the additional step of that bank crediting the actual customer account, often called the last mile, can take considerably longer. A transfer that looks fast on paper can still leave a recipient waiting.
How Long Does an International Transfer Take From India?
Transfers originating in India can involve a few extra considerations on top of the general process. Timing can be affected by:
- The type and purpose of the remittance
- The sending bank or authorised dealer
- Currency and destination country
- Required information and documentation
- KYC and compliance checks
- Applicable RBI and FEMA requirements
- Bank processing schedules and cut-off times
- Receiving-bank processing
For individual outward remittances, the Reserve Bank of India’s Liberalised Remittance Scheme (LRS) allows resident individuals, including minors through a guardian, to remit up to USD 250,000 per financial year for permitted current and capital account purposes, routed through an authorised dealer bank with a Form A2 declaration. This includes common purposes such as overseas education and maintenance of a relative abroad, though it should not be assumed that every international payment from India automatically falls under this exact process.
This is an important distinction for education and immigration consultants specifically, since an individual sending money directly to a recipient and a B2B intermediary handling a student’s payment on behalf of a business can follow different transaction structures. If you are unsure which framework applies to a specific payment, it is worth confirming directly with your bank or authorised dealer, since RBI and FEMA rules can be updated.
International Transfer Times by Transfer Method
The method used for a transfer changes how the payment moves, though it does not guarantee a fixed universal timeframe.
| Transfer Method | Timing Depends On | Common Use | Important Consideration |
|---|---|---|---|
| Bank transfer | Sending and receiving banks, corridor, cut-off times | Personal and business transfers | Bank processing schedules vary |
| Wire transfer | Banks, payment route, currency, compliance | Business and high-value payments | The exact route can differ between transactions |
| SWIFT | Beneficiary bank, local processing, compliance | Cross-border bank payments | Reaching the SWIFT network is not the same as final account credit |
| Digital remittance | Provider, funding method, destination, verification | Personal remittances | Processing is provider-specific |
| B2B international payment | Documentation, approval, compliance, banks | Business and intermediary workflows | Transaction structure can affect processing |
International Bank Transfers
A standard bank transfer depends on how quickly the sending bank processes the instruction, how the receiving bank handles it on arrival, and whether any intermediary or correspondent banks sit in between. Cut-off times and business days both play a role, and destination-country banking infrastructure can add further variation.
International Wire Transfers
“Wire transfer” describes a payment mechanism rather than one fixed processing time. Timing can vary depending on the banks involved, the currency, the destination, the payment route taken and any compliance checks applied along the way.
SWIFT Transfers
It helps to clear up a common misunderstanding here. SWIFT is primarily a financial messaging network that lets banks send payment instructions to each other. It does not itself hold or move the customer’s money.
Current SWIFT data shows that 75% of cross-border payments reach the beneficiary bank within 10 minutes, and around 60% are credited to the end beneficiary within 30 minutes, with almost 100% credited within 24 hours. But reaching the beneficiary bank is not the same as the money landing in the customer’s account. This final stretch, sometimes called the last mile, covers the beneficiary bank’s own local processing, operating hours, regulatory checks and internal systems, and it is where most of the remaining delay tends to sit.
Digital Remittance Services
Digital remittance providers often run their own processing models rather than relying purely on traditional bank rails. Timing here depends on the funding method used, the destination, the currency, the specific provider, verification steps and the receiving infrastructure at the other end. It is not accurate to assume digital transfers are automatically faster than a bank transfer in every case.
B2B International Payments
For education consultants, immigration consultants and businesses handling student fee-related transfers, the workflow can look different from a personal transfer. These payments often involve documentation, verification and internal approval steps before the payment is even sent, and a B2B intermediary managing a payment on behalf of a client may follow a different transaction structure than an individual sending money directly.
What Factors Affect International Transfer Times?
International transfer time is affected by a combination of banking, compliance and information related factors.
| Factor | How It Can Affect Timing |
|---|---|
| Business days | Processing may depend on banking operating days |
| Cut-off times | Instructions submitted after a cut-off may enter a later processing cycle |
| Weekends | Some banking and payment systems do not process on weekends |
| Public holidays | Local holidays can affect sending, intermediary or receiving institutions |
| Currency | Currency corridor and foreign exchange processes can add time |
| Destination | Local banking infrastructure and regulations differ by country |
| Intermediary institutions | Additional processing may occur along the payment route |
| Compliance | Additional checks can place a transaction on hold |
| Incorrect details | Errors can lead to delays, investigation or a returned payment |
| Receiving bank | Final crediting depends entirely on the beneficiary institution |
SWIFT specifically points to receiving-country regulations, local operating hours, domestic banking infrastructure, currency controls and manual processing as factors that most often affect this final stage of a cross-border payment.
Why Is My International Transfer Taking So Long?
If a transfer is taking longer than expected, it helps to work through where it might be stuck rather than assuming the worst.
| Possible Reason | What It Means | What to Check |
|---|---|---|
| Weekend or holiday | Processing may resume during the next banking window | Banking calendars |
| Cut-off missed | The instruction may have moved to a later processing cycle | Submission time |
| Compliance review | Additional checks may be required before the payment continues | Provider or bank communication |
| Incorrect information | The payment may need correction or investigation | Beneficiary details |
| Intermediary processing | Another institution may be involved in the route | Transfer status |
| Receiving-bank processing | Funds may have reached the bank but not yet been credited | Beneficiary bank |
| Currency or corridor issue | Local processing requirements can differ by corridor | Provider or bank |
| Missing documentation | Additional information may be requested | Provider request |
A few useful distinctions worth keeping in mind: pending does not necessarily mean something has failed, and delayed does not necessarily mean the money is lost. A returned payment simply means the funds are being sent back or the transaction could not be completed as instructed. Exact terminology can differ between providers, so it is worth checking what a specific status actually means with the bank or provider handling the transfer.
Do International Transfers Process on Weekends and Holidays?
This depends on the payment rail, the sending and receiving institutions, local banking hours, country-specific holiday calendars and whether the systems involved run 24/7. Not every international transfer stops completely over a weekend, but not every system operates around the clock either.
SWIFT notes that where beneficiary banks or domestic payment systems do not operate 24/7, a payment arriving outside normal business hours may only be credited on the next working day. So a payment sent on a Friday evening or right before a public holiday can sit ready at the receiving bank without being credited until the next working day opens.
How Can You Reduce International Transfer Delays?
While no one can guarantee a specific delivery time, a few practical steps can reduce avoidable delays:
- Verify the beneficiary’s account and bank details before submitting.
- Check the provider’s stated processing window in advance.
- Submit before relevant cut-off times where applicable.
- Account for weekends and public holidays on both ends.
- Complete any required verification or KYC steps early.
- Keep supporting documentation ready where it might be needed.
- Double check the currency and destination country details.
- Track the payment after it has been submitted.
- Respond quickly if the provider or bank requests additional information.
These steps can meaningfully cut down on avoidable delays, but they cannot guarantee a particular delivery time, since some factors, like receiving-bank processing or local regulations, are outside the sender’s control.
How Long Does a University Fee Transfer Take?
A university fee payment follows the same general process as any international transfer, but a few extra considerations come into play. Timing can depend on the payment method used, the university’s own receiving process, the sending bank or provider, currency, cut-off times, business days, payment references and any required documentation.
One important distinction here: a payment arriving at the university is not the same as it being reconciled against the student’s account. The transfer itself may reach the institution’s bank fairly quickly, while the university’s internal finance team still needs time to match that payment to the correct student record, especially during peak admission periods when volumes are high. This is a common source of confusion for students and consultants who assume the payment has failed simply because it has not yet appeared against the student’s account.
How Long Does Student Remittance Take?
Tuition fees, living expenses and other education-related transfers do not all follow identical timelines, since the transaction structure can differ. A tuition payment routed through a university’s designated payment partner may move differently than a personal transfer sent for a student’s monthly living expenses, so it is worth checking the specific process for each type of payment rather than assuming they behave the same way.
How Can You Track an International Transfer?
Tracking depends heavily on the specific provider and payment method used, so it is not identical across every transaction. Useful information to keep on hand includes:
- Transaction or reference number
- Payment confirmation from the sender’s bank or provider
- Current transfer status, where available
- Any tracking tools the provider offers
- Bank confirmation of receipt
- Confirmation from the beneficiary once funds arrive
SWIFT also provides payment tracking and visibility tools within its own network for participating banks, but this does not mean every consumer transaction automatically comes with the same level of tracking detail. It is worth asking your specific provider what tracking options are available before you send a payment, especially for time-sensitive transfers like tuition fees.
When Should You Contact Your Bank or Transfer Provider?
It is reasonable to reach out to your bank or provider when:
- The payment has exceeded its stated processing timeframe.
- The beneficiary has not received funds after the expected delivery window.
- The status remains pending with no explanation.
- Additional documentation has been requested and you are unsure what is needed.
- You suspect the beneficiary information may be incorrect.
- The transfer has been returned.
- The payment confirmation does not match what you expected.
When you do reach out, having the right details ready speeds things up considerably. Keep the transaction or reference number, the date and time of the transfer, the amount and currency, the beneficiary’s details, your payment confirmation and any prior communication from the provider close at hand. There is no fixed universal rule for how many days to wait before raising a concern, since this depends on the specific corridor and provider, so check the stated processing window for your transaction rather than following a generic timeframe.
How ZeoForex Helps Simplify International Money Transfers
ZeoForex is built primarily for B2B intermediaries handling international payments on behalf of others, particularly education consultants, immigration consultants and organisations managing student-related transfers. Rather than acting as a direct consumer remittance app, it fits into a workflow more like this:
Payment requirement → transfer details → verification and processing → international remittance → recipient or institution
Even within this workflow, transfer timing still depends on the underlying payment route, the destination country, the banking institutions involved, applicable compliance requirements and other transaction-specific details covered earlier in this article. ZeoForex does not offer a guaranteed same-day transfer, a guaranteed delivery time or a guaranteed exchange rate, since these outcomes depend on factors outside any single platform’s control.
What it does offer is a structured way for consultants and organisations to manage student fee and B2B remittances with clearer verification and processing steps built in, rather than piecing together the process manually for each transaction.
Need help with international student-related remittance? Explore ZeoForex or speak with the team about your specific requirements.
International Transfer Time FAQs
How long does an international transfer take?
It depends on the payment method, banks involved, destination, currency, cut-off times and compliance checks. There is no single timeframe that applies to every transfer.
How long does an international bank transfer take?
This depends on the sending and receiving banks, the corridor used and whether any intermediary banks are involved, along with cut-off times and business days.
How long does a SWIFT transfer take?
SWIFT data shows most payments reach the beneficiary bank within minutes, but the final credit to the customer’s account depends on that bank’s own local processing, which can take longer.
How long does an international transfer take from India?
It depends on the type of remittance, the authorised dealer bank, applicable RBI and FEMA requirements, documentation and the receiving bank’s own processing.
Why is my international transfer taking so long?
Common reasons include weekends or holidays, a missed cut-off time, a compliance review, incorrect beneficiary details or processing still happening at the receiving bank.
Why is my international transfer pending?
Pending generally means the payment has not yet completed processing. It does not necessarily mean something has gone wrong, though it is worth checking the status with your provider if it persists.
Do international transfers process on weekends?
Some payment systems operate 24/7 while others do not. Where a receiving bank or system is not available around the clock, a payment may only be credited on the next working day.
Do public holidays delay international transfers?
Yes, holidays can affect the sending institution, an intermediary or the receiving bank, depending on which calendar applies to each party in the transaction.
Can incorrect bank details delay an international transfer?
Yes, incorrect or incomplete beneficiary details are one of the more common causes of delays, investigation or a returned payment.
Do intermediary banks affect transfer time?
Yes, when a payment passes through one or more intermediary banks, each additional step can add processing time to the overall journey.
How long does a university fee transfer take?
It depends on the payment method and the university’s own receiving process, and the payment reaching the institution is not the same as it being reconciled against the student’s account.
How can I reduce international transfer delays?
Verifying beneficiary details, submitting before cut-off times, completing verification early and tracking the payment can all reduce avoidable delays, though they cannot guarantee a specific delivery time.
How can I track an international transfer?
Tracking depends on your specific provider. Keeping your reference number and payment confirmation on hand makes it easier to check status when needed.
When should I contact my bank about a delayed international transfer?
It is worth reaching out once a payment has exceeded its stated processing window or the status remains unexplained, especially if documentation has been requested.
Does the destination country affect international transfer time?
Yes, local banking infrastructure, regulations, operating hours and currency controls in the destination country can all affect how quickly a payment is finally credited.